Tag: HOUSING

  • Everybody’s talking about foreign investment; let’s talk about renter tax credits

    Everybody’s talking about foreign investment; let’s talk about renter tax credits

    Housing affordability: If it’s bad for buyers, it’s worse for renters.

    Early last week I attended the SFU Community Summit’s Housing in the City: Beyond the Headlines panel discussion on issues relating to housing in B.C. and efforts to move us closer to the goal of affordable, suitable, and secure housing for all.

    Each offering a different expertise, the speakers’ presentations ranged from First Nations housing; to community groups leveraging land assets to build affordable housing; to the economics of building more rentals. Christine McLaren from Happy City described urban design and social geometry for happier harmonious living (who knew—the ideal front yard for genial neighbourliness is exactly 10.6 feet deep). Marla Zucht from the Whistler Housing Authority explained how that resort municipality extracts housing from new developments to provide affordable rental and home-ownership for the people who work there. 

    There was a lot of anticipation as UBC geography professor David Ley rose to speak about foreign investment (or more specifically, as he distinguishes it: non-local capital).

    Earlier that day, urban planner and researcher Andy Yan had released a new report suggesting that almost three-quarters of detached home sales on the west side were to Mainland Chinese buyers. Yan was in the audience, and told me he was taking a lot of heat for his research, including accusations of racism from real-estate industry types and even the mayor. 

    In Yan’s defense, it is precisely the lack of data that he feels has the potential to incite racism, because in the absence of facts rumours and half-truths can flourish. I’m inclined to agree, and as I’ve previously proposed: we should better track and analyze the effects of non-local capital on our unaffordable housing, and adjust our available taxation tools to protect local residents by investing that revenue in affordable housing and work to prevent reported tax fraud. It’s important to note the majority of our regional real estate market is driven by and for locals (speculators or otherwise), but we still need to analyze the role of non-local capital, while repudiating xenophobia and racism.

    Even the B.C. New Democrats have done a full reversal on the issue of foreign capital. It was the NDP government who originally stopped collecting data on foreign and corporate real estate purchases, ironically out of a fear that foreign money might leave the region. Last month, speaking to her record as Vancouver-Mount Pleasant MLA, now-MP Jenny Kwan clarified her previous position protecting the privacy of investors hiding foreign assets with the goal of better collecting data about foreign ownership of local housing. 

    There doesn’t look to be any forthcoming meaningful action from the B.C. Liberals though. In case you missed the news release during the federal election, the governmenthas no intention of targeting non-local investors or house-flippers, although they are considering measures to further protect first-time buyers.

    Even if we did have decisive leadership and direction to mitigate and extract value from speculators, luxury properties and foreign and corporate investors—it’s a bit like closing the barn doors after the horses have gone. The Vancouver housing bubble is quite unlikely to contract in the near term, and those high prices that shut so many out of the market are here to stay for the foreseeable future. 

    But if it’s bad for buyers, it’s worse for renters.

    Those ever-inflating house prices aren’t just thwarting first-time-buyers, they are putting pressure on rentals. The latest CMHC data puts vacancy rates in Vancouver at below one percent. If you have multiple bedroom needs or pets, it’s even worse and it certainly isn’t affordable. The average rent in Vancouver rose 4.6 percent in 2015, twice the national average, making it the most expensive of any major metropolitan area in the country. Meanwhile our median income is among the lowest.

    The lack of affordable rental is a growing crisis which most analysts are predicting will get even worse as buyer potential is diminished. Savvy investors have anticipated this—between high demand and local governments’ willingness to bonus rental developments—they see real opportunity to make profit in the rental market.

    Arguably, increasing supply might temper our low vacancy rate, but there has very little market or government initiative to ensure those rentals are actually affordable. We can only hope that our new federal government’s promise of funding and incentives for new affordable housing will help to create more supply, which otherwise cannot be left to the market alone.

    Rent control is another obvious solution, but in a free enterprise housing market—where renovictions are a thing, and the provincial Residential Tenancy Act is in desperate need of overhaul—there is potential for pushback from industry. Arguably rent control could be seen as a disincentive for new rental builds, although cities like New York have managed to make renter protection a condition of rezonings. 

    But there is a tool that hasn’t been subject to much discussion in our province, one that might bring some relief to beleaguered British Columbians: a renter’s tax credit.

    The idea is simple enough: a provincial tax credit, means-tested and income adjusted, that could offset the burden of renting in unaffordable markets. 

    Renter tax credits are not a new idea—for millions of Canadians, renter tax credits are already available and working to alleviate their rent burden: in Quebec as the Solidarity Tax Credit, and in Ontario as part of the Ontario Trillium Benefit, where it is also tied to relieving the cost of energy use in remote communities. In the United States, after years of tax and lending policies directed to encourage homeownership, renter tax credits are being considered as a tool to promote equity and alleviate household poverty.

    Why not here in B.C? B.C. Housing does collect data on housing costs relative to income: the Housing Income Limits, published annually, track the income required to pay the average market rents in planning areas throughout the province. Here in Vancouver-Mount Pleasant, almost three-quarters of the population rent, half of those renters pay more than 30 percent of their income on rent, and a growing number of that cohort spend more than 50 percent. 

    There are many practical justifications for a tax credit, starting with housing equity and poverty relief. Our province consistently ranks above the national average for rates of child poverty. Food must often take a second place to rent and utilities: hunger and food insecurity in turn diminish productivity and health, ultimately costing our system in other ways. Those credits in turn are likely to return to our local economy either directly or indirectly. The indirect economic impact is most notably the ability for business to attract and retain employees. Experts predict that without meaningful intervention, housing unaffordability could trigger a labour crisis in parts of our province.

    There is need for further study. One unintended consequence of a renter tax credit might be to put pressure on landlords to declare their rental income and comply with local construction and residential by-laws. While at first glance this might seem like a fair and equitable consideration—in our city, with its sky-high property prices—mortgage helpers often take the form of undeclared suites and rentals; they make up an important part of the rental continuum, and we can’t afford to jeopardize them.

    Do the benefits of a renters tax credit outweigh the risks? Let’s urge some immediate provincial action to study the idea. 

    One thing is for sure, inaction is no longer an option and we need relief for renters, now.

    Special thanks to Grant Diamond at UBC School of Community and Regional Planning for his research help on this.

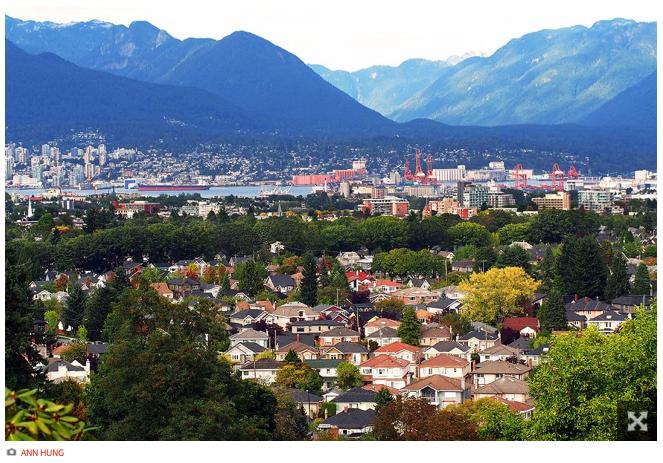
    Originally published in the Georgia Straight, Photo Ann Hung

  • Don’t penalize Vancouver seniors for government’s failure to curb runaway housing values

    Don’t penalize Vancouver seniors for government’s failure to curb runaway housing values

    Peter Ladner’s  Sept 14 opinion piece raises an interesting quandary about Vancouver housing prices, the dearth of detached homes, and the notion that taxpayers are subsidizing seniors to take up unused space.

    The idea of an octogenarian rattling around an underutilized, empty-bedroomed $3 million Dunbar bungalow while young families are forced out of the city makes for a convenient if not somewhat mean spirited scapegoat — but let’s take another look:

    Let’s imagine that an 80-year-old and her husband purchased their bungalow 40 years ago when the B.C. property tax deferment program was started. In 1985, interest rates were 13.25 per cent, purchase required a 25 per cent downpayment and the average price for a detached house in the city was $112,000. 

    In 1985, the Province of B.C. still collected data on foreign and corporate home purchases, so we would have thus known that our homeowners were tax-paying Canadian citizens and had purchased their first home for their growing family.

    In 1985, the housing market was just bouncing back from the crash of the early 1980’s, and Expo 86 hadn’t yet brought the world to our doorstep. Interest rates were cripplingly high, but our example family probably worked hard over the following decade, and maybe managed to save money to put their kids through university. 

    Perhaps fear of the past decade’s market crash had made the family risk adverse and reluctant to “trade up” as Vancouver’s housing market started along its steady exponential growth. Perhaps it was the scourge of leaky condos that had bankrupted many of their peers that left our couple skeptical about downsizing after the kids had left for college. Perhaps a reverse mortgage was secured to top up a meagre pension, or the comfort of familiarity helped mitigate the onset of senility.

    For whatever reason, our octogenarian has chosen to stay, be it in their Dunbar bungalow or two bedroom condo. It’s a stilted notion to suggest that they are staying in place because tax policies are subsidizing them to do so — they are able to stay in place because tax policies are protecting them from being forced out.

    The Property Tax Deferment Program exists to inure senior and/or disabled homeowners from market changes, when a fixed income likely means they wouldn’t be able to keep up with steadily increasing property assessment values and resultant property tax.

    These taxes aren’t being forgiven, they are being deferred to be paid on the ultimate sale of the home. 

    Should — as Ladner suggests — tax deferrals be means tested, consider residency history, and apply a more robust interest rate against the rebate at point of sale? Absolutely, but let’s be careful not to mischaracterize home-owning seniors as wealthy in the same breath as suggesting they are disadvantaging young families.

    Even without tax deferral, the market is squeezing young families out of the city. There is a certain irony that of all the other potential displacement factors: speculation, flipping, foreign investment and the luxury housing market — property tax deferment for seniors and disabled is the only one we are accurately tracking and monitoring. 

    It’s no secret that developers are running out of available land in Vancouver and that stagnant land is the antithesis of growth, so I’ll concede that there may be a very real business model to consider. If we want seniors to downsize and open up that market, let’s incentivize not penalize. And if we want to encourage housing affordability, let’s consider all the factors and enact sensible policies that will ensure housing for everyone in all stages of life.

    Originally published in Vancouver Courier

  • Lower interest rates and housing affordability, more danger ahead?

    Lower interest rates and housing affordability, more danger ahead?

    This morning, as predicted, the Bank of Canada cut our interest rate by .05 per cent. Ostensibly, the move is to head off a recession — spurred mostly by slumping oil markets that have dampened Alberta’s economic outlook — lower interest rates mean Canadians will spend more.

    Lower interest rates also mean cheaper mortgage rates, which in turn will push up housing prices, particularly as investors look for safe places to park their money, like Vancouver.

    Canada isn’t the only large land mass nation faced with a recession though. China is experiencing an economic slowdown and an extremely volatile stock market, which will spur investors there to look for safe places to park their money, like Vancouver.

    While other Pacific Rim nations and states (Australia, New Zealand, Singapore, Hong Kong, China) have shored up their real estate markets with tax and duty programs to protect housing stock for locals — British Columbia remains mired in a do-nothing holding pattern, citing insufficient data, lack of evidence, and possible impacts on existing homeowner equity.

    Meanwhile our housing bubble continues to grow, unfettered and unrestrained, waiting — like all bubbles do — to inevitably burst.

    I hate to sound like a broken record on this — but we need provincial leadership on this issue. Now.

    Over $1billion in provincial property transfer taxes are directed to general revenue rather than to affordable housing in the jurisdictions that are generating that wealth. Let’s take the advice of the BC Chamber of Commerce and others and fix our property transfer taxes, track corporate and foreign investment

    http://www.bloomberg.com/news/articles/2015-07-13/china-may-tip-world-in…

    http://www.theguardian.com/business/2015/jul/08/china-stock-market-crisi…

    http://news.ubc.ca/2015/07/14/another-cut-to-canadas-interest-rate-could…

    https://www.biv.com/article/2015/7/vancouvers-housing-market-doesnt-need…

    http://www.straight.com/news/455161/pete-fry-tackling-roots-vancouvers-h…

    http://www.straight.com/news/478496/pete-fry-housing-crisis-failure-gove…

  • Housing crisis is a failure of government, not the fault of investors

    Housing crisis is a failure of government, not the fault of investors

    My name’s Pete Fry, and I’m the BC Green Party candidate in the provincial riding of Vancouver-Mount Pleasant—where we’ll be holding a special by-election to replace Jenny Kwan now that she is running in the federal election.

    Last year, I ran for Vancouver City Council, and while I wasn’t elected: I did receive a lot of votes, especially considering it was a low budget and non-developer funded campaign. For those of you who aren’t familiar with the campaign—I ran on issues of community, environment, transparency, and affordability.

    And it’s those same issues that bring us all here today.

    We’ve all heard anecdotes about global capital and foreign ownership. I recently wrote about the market externalities affecting my own community of Strathcona. A well-financed west-side investor set about purchasing a number of homes in the neighbourhood: in cash, with no subjects or conditions, and always over the asking price.

    Strathcona has a limited land base, maybe 350 detached homes in all, and this particular investor may have purchased a dozen of them—about 5 per cent.

    Coincidentally, five per cent is about the same number that the BC Real Estate Association claim as the relatively insignificant amount of foreign ownership in Vancouver. A little higher at 5.8 per cent is the Canada Mortgage and Housing Corporation’s figure for percentage of foreign ownership in the downtown peninsula.

    Back in Strathcona, the effect of that five per cent unfettered non-local capital was to drive up the median home value, to the point that locals were priced out and the average house price increased with each bidding war. In turn, the increased demand for the limited stock of housing led to more speculation, and higher asking prices.

    A lot like Vancouver as a whole.

    In that respect, our real estate market is like a closed ecosystem. Finite resources exist in a delicate equilibrium; and externalities—in this case the influx of non local capital—can profoundly upset that balance, and lead to unintended consequences.

    Like that closed ecosystem analogy, the externalities are not unlike climate change, where even a few points of a degree of temperature increase can have catastrophic effects on weather, and aquaculture, and economic sustainability, and communities, and so on: a cascading litany of catastrophic consequences.

    Also like climate change, many of our leaders and those who are profiting from the status quo remain in denial about what is happening.

    That’s what we’re seeing today—externality driven housing prices profoundly out of synch with local incomes; the real threat of a generational brain drain and the inescapable conclusion that without intervention, our city is faced with severe social and economic consequences.

    For several years, respected urbanists and researchers have been warning of global capital upsetting our housing equilibrium. In the last several months, the BC Chamber of Commerce and VanCity Credit Union have cautioned that our affordability crisis is leading us to a dangerous and unsustainable future. Yet still, some in our government, development and real estate industries dismiss these concerns as at best anecdotal, at worst racist and xenophobic.

    Of course, racism, xenophobia and bigotry have no place in this important conversation, nor will they in the necessary solutions.

    As for anecdotes; it could be said that the antidote for the anecdote is data, and that’s true—but we also need action.

    Time is a luxury we do not have. We needed that data yesterday. Indeed a recent revelation in Douglas Todd’s Vancouver Sun blog: the former director of Land Titles revealed that we actually had that data yesterday—detailed information about corporate and foreign ownership in B.C. that was collected and stored for twenty years without any analysis. Even more shockingly, that data was apparently destroyed when they ran out of room to store it.

    Global real estate managers Knight Frank have named Vancouver a top property investment, they refer to it as a “safe haven market” for migrating wealth from economic or political crisis situations. Fund managers around the world are advising Vancouver is a great place to park your money, superior to gold and other commodities. As urbanist Andy Yan aptly describes it, we have become a hedge city.

    Around the Pacific Rim, similarly desirable global destinations have enacted protocols to leverage global investor capital and protect local populations: China, Hong Kong, Singapore, Australia, New Zealand—as of last month our region now stands virtually alone as an attractive target for the unfettered flow of global investment.

    This isn’t the fault of global investors—it’s the failure of local government.

    British Columbia collects some $1billion annually in property transfer taxes—taxes that are largely borne by our astronomical real estate prices, and at the expense of our local affordability.

    Those taxes go toward the province’s general revenue—when in fairness, they should be redirected back to the municipalities that are generating them. Let the municipalities determine how best to spend that revenue: in some cases it may be a rebate to encourage foreign investment, but in the case of Vancouver and our urban centres, I’d suggest it be channeled into affordable housing.

    That’s just one solution, one of a several we should be employing on a provincial level. Mayor Gregor Robertson and Bob Rennie’s recent suggestions of a speculator tax will be helpful in addressing the issue of quick-sale house flipping for profit. We also should be including a foreign investment duty, as well as a luxury property purchase duty as part of a robust toolkit of measures to protect our local affordability.

    If we look around at the pace of development in Vancouver, we see rezoning for more growth and densification as a means to extract Community Amenity Contributions. Increasingly as senior governments offload the responsibility of building housing, cities are turning to these contributions as a means to provide affordable housing. Last year in Vancouver, these CACs amounted to some $232 million—over half of which was directed to affordable housing, at the expense of things like parks and community centres.

    In order to extract Community Amenity Contributions to build affordable housing, the city must rezone the land and in the process increase it’s value—and thereby increasing the value of the surrounding area. It’s a process referred to as “land-lift” and precipitates a vicious cycle of higher prices for property in order to subsidize affordable housing that can’t possibly be built fast enough. It’s clear our city can’t go it alone—we need senior government intervention.

    Vancouver’s crisis of today is Victoria’s crisis of tomorrow, and quickly spreading to other regions of our province, particularly as Vancouverites are priced farther and farther out of the city. 

    Some will argue that any sort of market intervention may have deleterious effects on existing homeowner equity.

    I’d argue that gentle intervention now and on our terms is preferable to hard intervention that might come in the form of global collapse or rising interest rates that would find many Vancouverites dangerously overextended and risk a housing continuum that includes not just primary home ownership, but private rental stock as well. We don’t want to pop the bubble, just deflate it a little bit.

    This is why we elect governments, to provide sound fiscal management and regulation—not to operate hands-off like the Wild West.

    Today, gathering together, this movement is a good start, pressuring the political will to act and to respond. We need to keep up that pressure.

    We have a federal election coming—talk to your prospective MP. We need a national housing strategy. Let’s get the Government of Canada back into building housing.

    My by-election is in six months, but there will be a general provincial election in 2017. The province has the ability to leverage property taxes to protect and enhance affordable housing—we need to keep advocating for that.

    I’ll add one final notion to consider; while the grim prospects for middle class home ownership have captivated the media, galvanized the public, and panicked the politicians—for a number of Vancouverites, affordable home ownership will never be an option. For a number of Vancouverites, even secure affordable rental housing will never be an option. We all need to come together united to ensure housing justice for all Vancouverites. As they say: a rising tide lifts all boats.

    There’s a wonderfully pithy piece of public art just down the street, it was commissioned of artist Kathryn Walter by the Contemporary Art Gallery back in 1990. It’s a text-based work, fronting The Del Mar Hotel. The Del Mar is an affordable housing building that famously held out when BC Hydro was redeveloping that block in the 1980’s, and now sticks out like a quaint Edwardian brick anachronism, surrounded by glass and concrete towers. I use that image on my social media as a poignant reminder of what is at stake.

    It reads simply “Unlimited Growth Increases the Divide”.

    It was true then, it’s true now, and it will be true tomorrow—let’s not let it be our city’s epitaph.Postscript: 

    Originally published in the Georgia Straight, based on a speech prepared for rally at Library Square organized by Vancouverites for Affordable Housing.

  • Vancouver Housing Bubble Trouble Needs Thoughtful Regulation

    Vancouver Housing Bubble Trouble Needs Thoughtful Regulation

    I was cautiously optimistic to hear the premier’s May 30 announcement that the B.C. Liberal government has begun researching the options for taking action on the issue of unaffordable housing prices.

    Housing affordabilty in Vancouver isn’t really news, of course. Since the federal government stopped funding new social housing in 1993, we’ve seen increasing pressure on low income Vancouverites. Today, after fifteen years of low interest rates and steadily increasing housing prices in Vancouver, what was once a social justice issue for this city’s most vulnerable and their allies, is increasingly taking its toll on middle-income owners — and the politicians and pundits are taking notice.

    In the days leading up to May 24’s #DontHave1Million rally, both Vancouver Mayor Gregor Robertson and condo marketer Bob Rennie called on the province tointroduce a speculator tax. A petition calling for restrictions on foreign investment has reached almost 25,000 signatures.

    The business and financial community are warning that housing affordability in Vancouver is quickly cascading into a crisis with long term negative repercussions. Last year, the B.C. Chamber of Commerce clearly identified the region’s attraction for global and speculative investment necessitated property tax reform. Just two weeks ago, Vancity credit union offered a warning that housing affordability risks cascading into a labour crisis putting public services and the region’s future economic development at risk.

    A recent New Yorker article explored the phenomenon of “high rent blight” where increasing rents and decreasing affordable housing are creating high priced districts devoid of local retail — and it’s not hard to imagine a similar fate befalling Vancouver.

    These are the canaries in the coal mine — the indicators are all around us, this crisis shows absolutely no sign of abating, and while calls for speculation tax are helpful, as uncomfortable as it may be, we need to have the conversation about the influence of non-local capital.

    Critics warn that the foreign investment discussion is inherently racist, as much of that capital — some of it illegally transferred “hot money” — is from China. It’s important to be resolute against xenophobia and racism, but it would be irresponsible of us not to take an honest and realistic look at foreign investment, regardless of where it is coming from.

    As I argued in my campaign for city council last year, and most recently in myGeorgia Straight commentary, foreign investment alone is not the source of our affordability crisis but it certainly is a factor.

    While there is a lack of comprehensive data, there is compelling enough information — from Canada Mortgage and Housing Corp.’s assertion that 5.8 per cent of downtown housing units are foreign owned, to revelations that over 35 per cent of the “hotly anticipated” Vancouver House development has been sold to foreign buyers.

    In his 2014 annual Vancouver developer industry luncheon speech, Bob Rennie famously mused of Vancouver real estate that “the top 20 per cent that have nothing to do with local incomes. They are for rich guys and foreign money.”

    By that notion, those top 20 per cent have everything to do with local housing affordability. West-side prices are driving higher income earners to East Vancouver, who are in turn driving up housing values. It’s a concept that UBC Geography professor David Ley describes as the “trickle-down effect” — where the introduction of external capital is driving a market that has disconnected from local incomes.

    Prime property investment cities like ours — the kind global real estate consultants Knight Frank describe as safe havens for wealth preservation in real estate — are increasingly seeking government intervention to preserve housing for local residents. Hong Kong, Singapore, China, Australia, and (as of May 17) New Zealand have all enacted measures to control speculation, foreign investment, and reign in runaway housing prices.

    Here in B.C., Finance Minister Mike de Jong warned that regulating or depressing prices could backfire and mean a reduction in equity for BC homeowners.

    I checked with Matt Toner, a former economist for the Bank of Canada and B.C. Green Party critic for finance and new economy. Matt emphasized that responsible regulation is very much the role of government: “It is crucial to distinguish between popping a speculative bubble (which can and likely will happen strictly due to market forces) and slowing/flattening the rate of growth of the bubble. Policy should be active and aimed at heading off the possible collapse of this real estate bubble.

    “Heaven help us all if government does nothing and this real estate bubble pops because of off-shore factors,” he said. “This inaction would make for a real made-in-B.C. recession, the effects of which the entire economy would be feeling for years.”Postscript: 

    Originally published in the Huffington Post